Financing, made honest
See exactly what your payment buys.
Drag the sliders and watch your buying power update instantly.
Build your payment
The price of the home you're considering
$100,000
National 30-yr conforming rates vary daily
Your monthly payment
$6,672/mo
Estimated total PITI at $1,000,000
Estimates only, not a loan commitment. Taxes, insurance, HOA, and PMI vary by county, lender, and property.
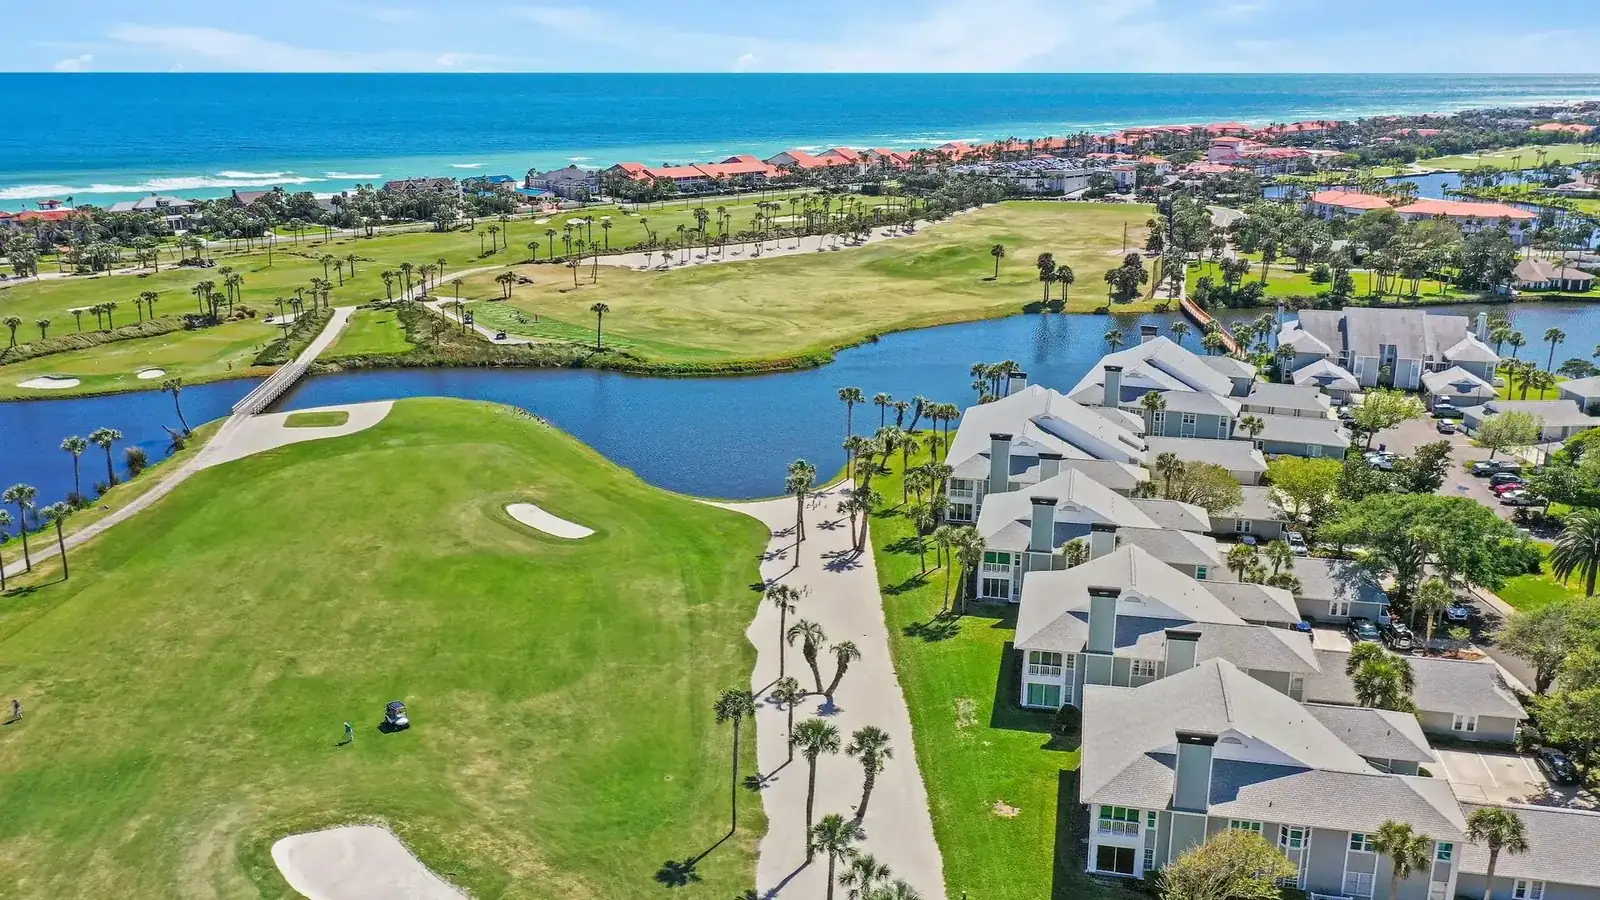
What this buys in Northeast Florida
Your community shortlist
Choose your preferred area and property type to see your shortlist.
Loan type, in plain English
Which loan probably fits you?
Conventional
3% - 20%+
Stable income, decent credit, planning to stay 5+ years.
The most common loan. PMI drops off at 20% equity.
FHA
3.5% min
Rebuilding credit or tight on down payment.
More flexible underwriting; mortgage insurance for the life of the loan.
VA
0% down
Eligible veterans, active duty, and surviving spouses.
Best terms available, no PMI, competitive rates, capped fees.
USDA
0% down
Buying in eligible rural areas.
Income limits apply in qualifying rural areas.
Financing shapes what you can offer and how fast you can move. In Ponte Vedra Beach, where strong listings draw interest quickly, a buyer who already has financing sorted tends to write a cleaner offer. We help you get there before you fall for a house.
Where financing fits in the plan
We start with a strategy session, not a listing link. Part of that conversation is money. How much you want to put down, how you want the monthly number to feel, whether you are buying before you sell or after. Once we understand the shape of your purchase, the loan conversation gets simpler.
We do not lend, and we do not give tax advice. What we do is connect you with lenders we have worked with across Ponte Vedra Beach, Nocatee, and the Jacksonville Beaches, then stay in the loop so the loan and the contract move on the same clock.
Getting pre-approved before you shop
A pre-approval tells you the price range the bank will actually back, and it tells a seller you are serious. Those are two different jobs. The first keeps your search honest. The second matters most when more than one buyer wants the same home.
Talk to a lender early, even if your move is months out. A good one will point out anything worth fixing in your credit or your paperwork while there is still time to fix it.
How we work with your lender
You pick the lender you trust. If you want introductions, we have several we recommend and will send names when you ask. From there we keep the file moving, flag dates before they become problems, and make sure the appraisal and inspection timelines line up with your closing. Calm, not chaos. That is the whole point.
Common questions about paying for your home
Do I need to be pre-approved before we look at homes?
We recommend it. A pre-approval sets your real price range and makes your offer stronger when a home draws more than one buyer. You can look at a few homes first to get your bearings, but have the pre-approval in hand before you write.
Can you recommend a lender?
Yes. We work with several lenders in the Ponte Vedra Beach and Jacksonville area and will send introductions when you ask. You are free to use your own bank or anyone else. The choice is yours.
What are closing costs like for buyers in Florida?
Closing costs cover lender fees, title, recording, and prepaid items like insurance and taxes. The exact figure depends on your loan and price, so we will have your lender and the title company give you a written estimate early. We would rather you see real numbers than a guess.
Should I sell my current home before I buy the next one?
Most of our clients are more comfortable knowing their sale proceeds before they commit to a purchase. If you need to buy first, there are financing routes that bridge the gap, and your lender can walk you through what qualifies. We will build the timeline around whichever order you choose.
Can you help with questions about taxes on a sale or an inherited home?
We can raise the issues worth asking about, then point you to a CPA for the answer. We do not give tax or legal advice. If you need a referral, we are glad to introduce one.
Start with a conversation
Tell us where you are in the process and we will tell you the next sensible step, whether that is a lender introduction or a full strategy session. Reach out here and we will follow up.
Financing questions, answered.
How is my monthly payment calculated?+
Your monthly mortgage payment includes four parts (PITI): principal, interest, property taxes, and homeowners insurance. Many lenders also collect for HOA dues separately. This tool estimates PITI using a 1.0% annual property tax rate and roughly $150/month for insurance.
What does it really cost to buy a home?+
Beyond your down payment, plan on 2 - 4% of the purchase price for closing costs, plus inspections, an appraisal, and your first year of homeowners insurance. We review every line item with you before you write an offer.
Is it better to buy now or wait for lower rates?+
There is no universal answer, it depends on how long you'll stay, your rent, and what inventory looks like in your price band. We run a real break-even side-by-side instead of guessing.
Which loan type is right for me?+
Conventional fits most buyers with stable income and 5%+ down. FHA helps when credit is rebuilding or down payment is tight. VA is the strongest option for eligible veterans. USDA works in qualifying rural areas. We will connect you with a lender who explains all four, not just one.
Do you have a preferred lender?+
We have a short list of lenders we trust because they communicate, close on time, and treat our clients well. You're never obligated to use them, but if you'd like introductions, we're happy to make them.